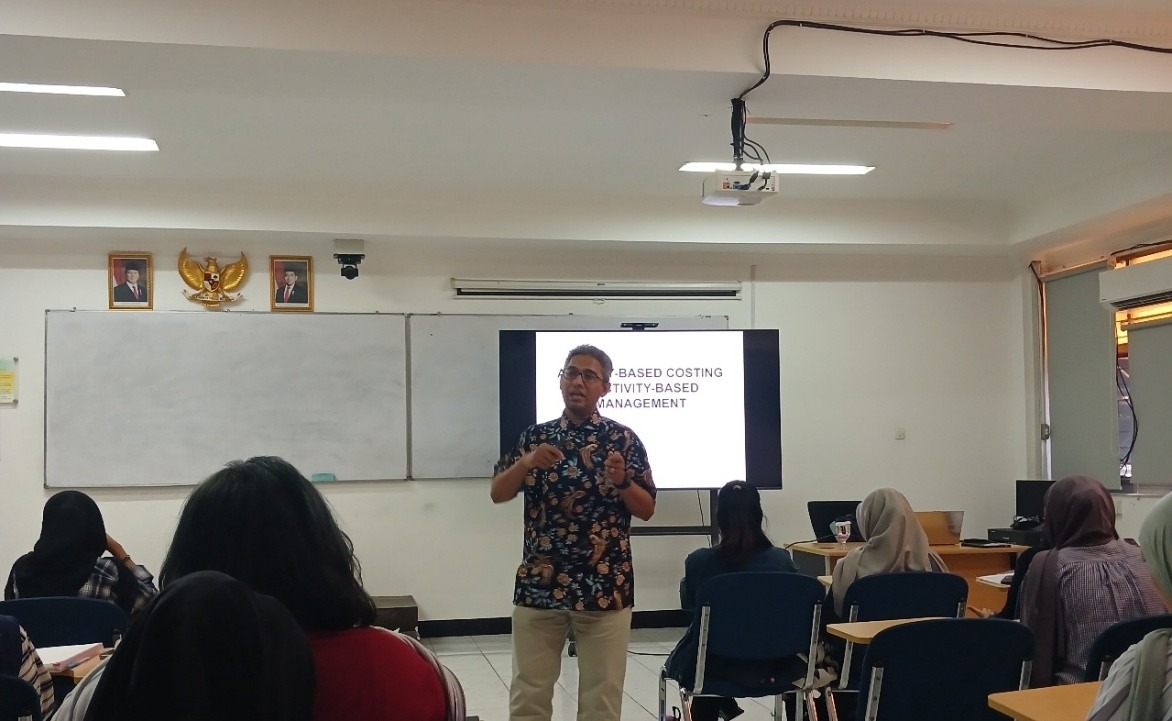
FEBUPNVJ – Management Accounting lecture in the third diploma accounting study program was held on Monday, September 14 2026, by Prof. Zubir from Universiti Sains Malaysia (USM). The session focused on Activity-Based Costing (ABC) and Activity-Based Management (ABM), giving students the opportunity to deepen their understanding of activity-based approaches to cost allocation, operational improvement, and managerial decision-making.
The lecture began with the fundamental concepts of ABC, which identifies activities within an organization and assigns costs to products and services based on their actual resource consumption. Students also explored the role of cost drivers, such as direct labor hours, machine hours, and the number of purchase orders, in determining activity-based overhead rates
The discussion then moved to Activity-Based Management (ABM), which extends the use of ABC information beyond product costing to support cost reduction, operational efficiency, and customer value creation. Students learned to distinguish between value-added and non-value-added activities and examined how organizations can improve their processes by reducing or eliminating activities that do not contribute to customer value.
Through case studies involving manufacturing and service organizations, students were introduced to the practical implementation of ABC/ABM, including its benefits and challenges. Key benefits highlighted included more accurate cost and pricing information, more efficient use of resources, and improved managerial decision-making, although implementation was noted to require significant resources, expertise, and organizational support.
The session concluded with an interactive discussion and encouraging students to relate the concepts covered to real-world challenges in cost management.
Overall, the lecture strengthened students’ understanding of contemporary cost management practices and provided valuable insights into applying ABC and ABM to improve organizational performance.